Currently Browsing: Personal Finance
Posted by Managementguru in Personal Finance
on Jul 16th, 2026 | 0 comments

For high earners, investment performance is typically measured by one figure alone: annual returns. However, while year-on-year growth is vital, it paints only part of the picture. Long-term financial success is a mixture of different colors, one which considers risk, taxes, diversification, and changing financial goals – not simply those short-term gains. This guide explains why. Risk-Adjusted Returns Matter Just as Much Generating strong returns during a rising market is one thing, but preserving wealth during periods of volatility is equally imperative. Take a portfolio that delivers slightly lower gains during strong years. This could still outperform over the long term if it experiences smaller losses during market downturns. When you evaluate investments through a risk-adjusted lens, it delivers a clearer scenario of how consistently a portfolio performs across different market conditions. Instead of backing higher-risk opportunities that can produce unpredictable results, this approach opens the door to steadier long-term wealth accumulation. Tax Efficiency Can Enhance Overall Outcomes It is common knowledge that taxes can significantly impact long-term investment performance, particularly for individuals with higher incomes and larger portfolios. While taxes cannot be avoided, thoughtful planning has the power to reduce unnecessary liabilities and allow more capital to remain invested. Take strategies such as tax-loss harvesting, careful asset location, and managing the timing of investment sales. Incorporate these, and they can all contribute to stronger after-tax returns. Look beyond those headline performance figures, and you can comprehend how much of your investment growth you’ll truly retain. Financial Priorities Evolve It’s rare for investment objectives to stay the same throughout your career. For instance, early on, professionals typically prioritize capital growth. Then during later stages of life, they place greater emphasis on preserving wealth and managing downside risk. As retirement approaches, reviewing whether your portfolio lines up with these changing priorities becomes increasingly important. For investors, incorporating a retirement income strategy alongside growth-focused investments can provide a more balanced approach. That’s because it supports long-term income needs without losing sight of continued capital appreciation. Diversification Should Extend Beyond Asset Classes Diversification is regularly associated with spreading investments across stocks, bonds, and cash. However, a well-rounded portfolio can also benefit from diversification across sectors, regions, investment styles, and sources of return. By casting a wider net, it reduces dependency on the performance of any single investment or market segment. That means, during periods when one area underperforms, others might step in to supply greater stability. It contributes to a smoother investment journey overall. Just remember that diversification isn’t about eliminating risk. Instead, the aim is to create a better-positioned portfolio to navigate changing economic conditions. A Long-Term Perspective Supports Better Decisions Yes, short-term market movements attract the most attention. Yet successful investing rewards patience rather than frequent reaction. When you make investment decisions based solely on recent performance, it can result in unnecessary portfolio changes that interrupt your progress. By sticking with a disciplined strategy based on clearly defined objectives, you can respond more thoughtfully to changing market conditions. Forget about chasing the strongest annual returns. You can achieve better long-term outcomes with a portfolio built around growth and adaptability throughout every stage of your financial...

Posted by Managementguru in Financial Management, How To, How to make money online, Personal Finance
on Feb 7th, 2026 | 0 comments
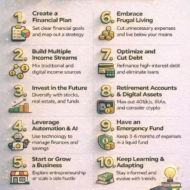
As we move into 2026, achieving financial independence has become more accessible thanks to technology, automation, and new income models. However, it still requires planning, discipline, and smart decision-making. Financial independence is the ability to cover your living expenses through investments, businesses, or passive income – without depending entirely on a paycheck. For many people, it represents freedom, flexibility, and long-term security. This guide explores 10 practical, modern ways to achieve financial independence, using real-world examples and strategies that work in today’s economy. What Is Financial Independence? Financial independence means having enough income from non-traditional sources — such as investments, businesses, or digital assets – to support your lifestyle indefinitely. It does not mean being ultra-wealthy. For some, it means covering basic expenses. For others, it means replacing full employment income or having the freedom to choose how and where they work. 1. Create a Clear Financial Independence Plan A financial independence plan defines: Your target monthly expenses Your savings and investment goals Your timeline and risk tolerance For example, someone earning $60,000 a year might set a goal to save 25% of income while gradually increasing investments over five years. The key is defining what “financial independence” actually means for you – whether it’s covering basic expenses, replacing full income, or achieving location-independent work. Using budgeting tools or financial planning apps ( YNAB, Quicken or simple goal-tracking tools) helps track progress and identify gaps. Many people begin by calculating their “financial independence number” – the amount needed to generate sustainable income. 2. Build Multiple Streams of Income One of the most effective ways to reach financial independence faster is by building multiple income streams. Even modest side income can accelerate financial independence. A $500 monthly side income invested consistently can grow significantly over time. Examples include: Freelancing or consulting Rental or real estate income Dividend-paying investments Digital products or subscriptions In 2026, many professionals earn income from portfolio careers, combining traditional work with online or scalable income sources. 3. Invest Consistently for Long-Term Wealth Investing remains a cornerstone of financial independence. Investing remains one of the most powerful tools for building long-term wealth. While trends change, the fundamentals stay the same: diversification, consistency, and time. Many people start with low-cost index funds that track the overall market. Others diversify into real estate investment trusts (REITs), global funds, or bond allocations for stability. A real-world example: investors who consistently contributed to broad index funds between 2010 and 2020 saw strong long-term growth despite short-term volatility. The lesson? Time in the market often matters more than timing the market. Popular options include: Index funds and ETFs Retirement accounts (401(k), IRA equivalents) REITs and diversified portfolios 4. Use Automation and AI to Manage Money Automated savings, investing, bill payments, and budgeting tools reduce friction and decision fatigue. AI-powered finance tools can track spending patterns, optimize savings, and even suggest portfolio rebalancing. For instance, automatically investing every payday ensures consistency without relying on motivation. Automation turns good intentions into habits. In 2026, AI-driven tools help with: Automated investing and savings Expense tracking and budgeting Portfolio optimization By automating financial decisions, you remove emotional barriers and maintain consistency – a major advantage over manual systems. 5. Start or Scale a Business Entrepreneurship is no longer limited to storefronts or large startups. Many people now build lean, digital-first businesses alongside traditional work. Digital-first businesses allow individuals to: Operate remotely Scale without large overhead Build recurring income Examples include: Online education or coaching Niche content websites E-commerce brands Subscription-based services Even small businesses can scale efficiently with automation and digital platforms. Many creators and solopreneurs today generate predictable income without large teams or overhead. 6....
Posted by Managementguru in Financial Management, How To, Personal Finance
on Apr 15th, 2025 | 0 comments

Managing finances effectively requires a structured approach across different timeframes—daily, weekly, monthly, quarterly, and annually. By using the right tools and habits, you can stay on top of your spending, savings, and long-term goals. Below is a bullet list outlining key financial tasks for each period, along with popular apps to streamline the process. Whether you’re tracking daily expenses or planning for retirement, these steps can help you build a solid financial foundation. Daily Track spending: Monitor transactions to stay within budget. Apps: Mint, YNAB (You Need a Budget), PocketGuard Check account balances: Ensure no overdrafts or unusual activity. Apps: Your bank’s mobile app, Chime, Venmo Categorize expenses: Log cash or small purchases for accuracy. Apps: Expensify, Spendee Weekly Review weekly budget: Assess spending patterns for the week. Apps: Mint, Goodbudget Pay small bills: Handle recurring subscriptions or utilities due weekly. Apps: Prism, Bill.com Update savings goals: Adjust contributions based on weekly income. Apps: Qapital, Digit Monthly Pay major bills: Cover rent, mortgage, utilities, and credit card payments. Apps: Your bank’s bill pay, PayPal, Rocket Money Reconcile accounts: Match transactions with bank statements. Apps: Quicken, Personal Capital Analyze spending trends: Identify areas to cut back or invest. Apps: Tiller Money Contribute to savings/investments: Automate transfers to savings or brokerage accounts. Apps: Acorns, Wealthfront, Betterment Quarterly Review investment portfolio: Rebalance stocks, bonds, or ETFs as needed. Apps: Vanguard, Fidelity, Robinhood Update financial goals: Adjust for life changes (e.g., job, marriage). Apps: Personal Capital, Monarch Money Check credit report: Look for errors or fraud every few months. Apps: Credit Karma, Experian Tax planning: Estimate quarterly taxes if self-employed or adjust withholdings. Apps: TurboTax, QuickBooks Annually File taxes: Prepare and submit federal/state tax returns. Apps: TurboTax, H&R Block, TaxAct Review insurance policies: Update coverage for health, auto, or home. Apps: Policygenius, Lemonade Assess net worth: Calculate assets minus liabilities to track progress. Apps: Personal Capital, Wealthfront Plan major financial goals: Budget for big purchases, retirement, or education. Apps: Morningstar, New Retirement Revisit estate planning: Update wills, beneficiaries, or trusts. Apps: Trust & Will, LegalZoom By breaking down financial management into daily, weekly, monthly, quarterly, and annual tasks, you can maintain control over your money and work toward long-term security. The apps listed above simplify these processes, from tracking daily expenses to planning for retirement. Consistency is key—regularly reviewing and adjusting your approach ensures you stay aligned with your goals. If you have specific apps or financial priorities, I can refine this plan to better suit your...
Posted by Managementguru in Financial Management, Personal Finance, Small Business Owners
on Feb 4th, 2025 | 0 comments

Achieving financial freedom within five years may seem ambitious, but it is entirely possible with a strategic approach. By automating savings, investments, and budgeting, coupled with disciplined money habits and savvy investment choices, you can set yourself on a path to financial independence. This article outlines a comprehensive and unique approach to achieving this goal. Automate Savings Automating savings is a crucial step towards building wealth effortlessly. Set up automatic transfers from your checking account to a high-yield savings account. Aim to save at least 20% of your income. Utilize apps like Qapital or Digit to round up purchases and save the spare change. This strategy ensures consistent savings without the temptation to spend. Smart Investments Investing is a powerful way to grow your wealth. Diversify your investment portfolio by including stocks, bonds, mutual funds, and ETFs. Consider robo-advisors like Betterment or Wealth front for automated, low-cost investment management. For those interested in more active investing, apps like Robinhood or E*TRADE offer easy access to the stock market. Remember to reinvest dividends and take advantage of compounding interest. Budgeting Made Easy Creating and sticking to a budget is essential. Use apps like You Need a Budget (YNAB) or Mint to automate and track your spending. Categorize your expenses and set limits to avoid overspending. Regularly review and adjust your budget to align with your financial goals. By automating your budgeting, you can better manage your cash flow and allocate funds towards savings and investments. Cultivating Money Habits Developing good money habits is key to long-term financial success. Pay off high-interest debts first to reduce financial stress. Use credit cards responsibly to earn rewards but always pay the balance in full each month to avoid interest charges. Practice mindful spending by distinguishing between needs and wants. Regularly review your financial goals and celebrate milestones to stay motivated. Exploring Crypto Investments Cryptocurrencies offer an exciting investment opportunity, albeit with higher risk. Allocate a small portion of your investment portfolio (e.g., 5-10%) to cryptocurrencies like Bitcoin or Ethereum. Use platforms like Coinbase or Binance for secure trading. Stay informed about market trends and regulatory developments to make informed decisions. Remember, crypto investments should complement, not replace, traditional investments. Trading in the Stock Market Stock market trading can be lucrative if approached wisely. Educate yourself on market fundamentals, technical analysis, and trading strategies. Start with paper trading or a small investment to gain experience. Use trading platforms with advanced tools and resources. Keep emotions in check and avoid impulsive decisions. Consistent learning and disciplined trading can yield significant returns over time. Conclusion Achieving financial freedom in five years requires a combination of automated savings, smart investments, disciplined budgeting, good money habits, and exploring emerging opportunities like crypto and stock market trading. By following these strategies, you can build a robust financial foundation and enjoy the freedom to pursue your dreams without financial constraints. Remember, the journey to financial freedom is unique to each individual. Tailor these strategies to your personal circumstances and stay committed to your goals. With determination and the right approach, financial freedom is within your...
Posted by Managementguru in Financial Management, How To, Personal Finance, Technology
on Aug 9th, 2024 | 0 comments

Financial planning has become crucial for all age groups, including children. Parents increasingly recognise the importance of early financial education and investment. This trend leads to a rise in demat accounts for minors, which allows parents to invest in their children’s future. But what does the future hold for these accounts and financial planning for kids? Future Trends The future of a minor demat account looks promising. One expected trend is the integration of technology. Fintech companies are developing user-friendly apps to manage these accounts. This technology will make it easier for parents and children to track investments. Another trend is personalized financial planning. Financial advisors offer tailored plans based on the child’s needs and goals. This customized approach ensures better returns and aligns with the family’s financial objectives. Furthermore, regulatory changes are anticipated. Authorities may introduce policies to make these accounts more attractive. These changes could include increased tax benefits and simplified processes. Such developments will likely boost the popularity of these accounts. Technological Advancements Digital Onboarding and KYC Processes One of the most impactful trends is streamlining the onboarding process for this demat account. Digital Know Your Customer (KYC) processes are becoming more sophisticated, allowing for a smoother and quicker account setup. Biometric verifications, AI-driven document checks, and seamless online interfaces reduce the time and effort required to open a demat account. This trend enhances user experience and ensures compliance with regulatory standards. Mobile Investment Platforms Another significant trend is the proliferation of mobile investment platforms tailored for minor demat accounts. These platforms are designed to be user-friendly and educational, enabling minors to understand and manage their investments with ease. Features such as interactive tutorials, gamified learning experiences, and real-time market updates are becoming standard. As smartphones continue to dominate, these mobile platforms will play an important role in shaping the investment habits of the younger generation. Regulatory Changes Simplified Compliance Requirements Regulatory bodies recognize the importance of financial inclusion for minors and work towards simplifying compliance requirements for these demat accounts. Reduced documentation, relaxed investment limits, and more straightforward transfer processes are being implemented to encourage parents and guardians to open demat accounts for their children. Enhanced Protection Mechanisms To ensure the safety and security of minor investments, regulators are introducing enhanced protection mechanisms. These include stricter guidelines for account monitoring, mandatory parental consent for significant transactions, and better fraud detection systems. By prioritizing the security of these demat accounts, regulators aim to build trust and encourage long-term investment practices from an early age. Educational Initiatives Financial Literacy Programs Financial literacy is a cornerstone of adequate investment. Educational institutions and economic organizations increasingly offer financial literacy programs aimed at minors. These programs cover essential topics such as the basics of the stock market, the importance of saving and investing, and the risks associated with different types of investments. Parental Involvement and Guidance Parents and guardians play a pivotal role in the financial education of minors. The trend towards greater parental involvement is gaining momentum, with many financial platforms providing resources and tools to help parents guide their children through the investment landscape. These resources include educational content, interactive financial planning tools, and forums for parents to share experiences and advice. The Role of Technology in Education The use of interactive learning tools is revolutionizing financial education for minors. Platforms offering simulations of stock market scenarios, virtual trading environments, and quizzes make learning about investments engaging and effective. These tools help minors understand complex financial concepts through practical, hands-on experiences, bridging the gap between theoretical knowledge and real-world application. The future of a minor demat account and financial planning for children is bright. As more parents recognise...